This is the first of my monthly editor's notes, sharing my view on what is happening in the financial and economic world. I will always try my best to keep these write-ups short and to the point.
Quick caution: The thoughts shared here completely reflect my personal views as of the day of writing, based on my current information and understanding. This is not formal financial advice or a specific product recommendation.
My goal is simply to keep these insights candid and easy to follow. Please feel free to reach out with any questions; I am always happy to chat.
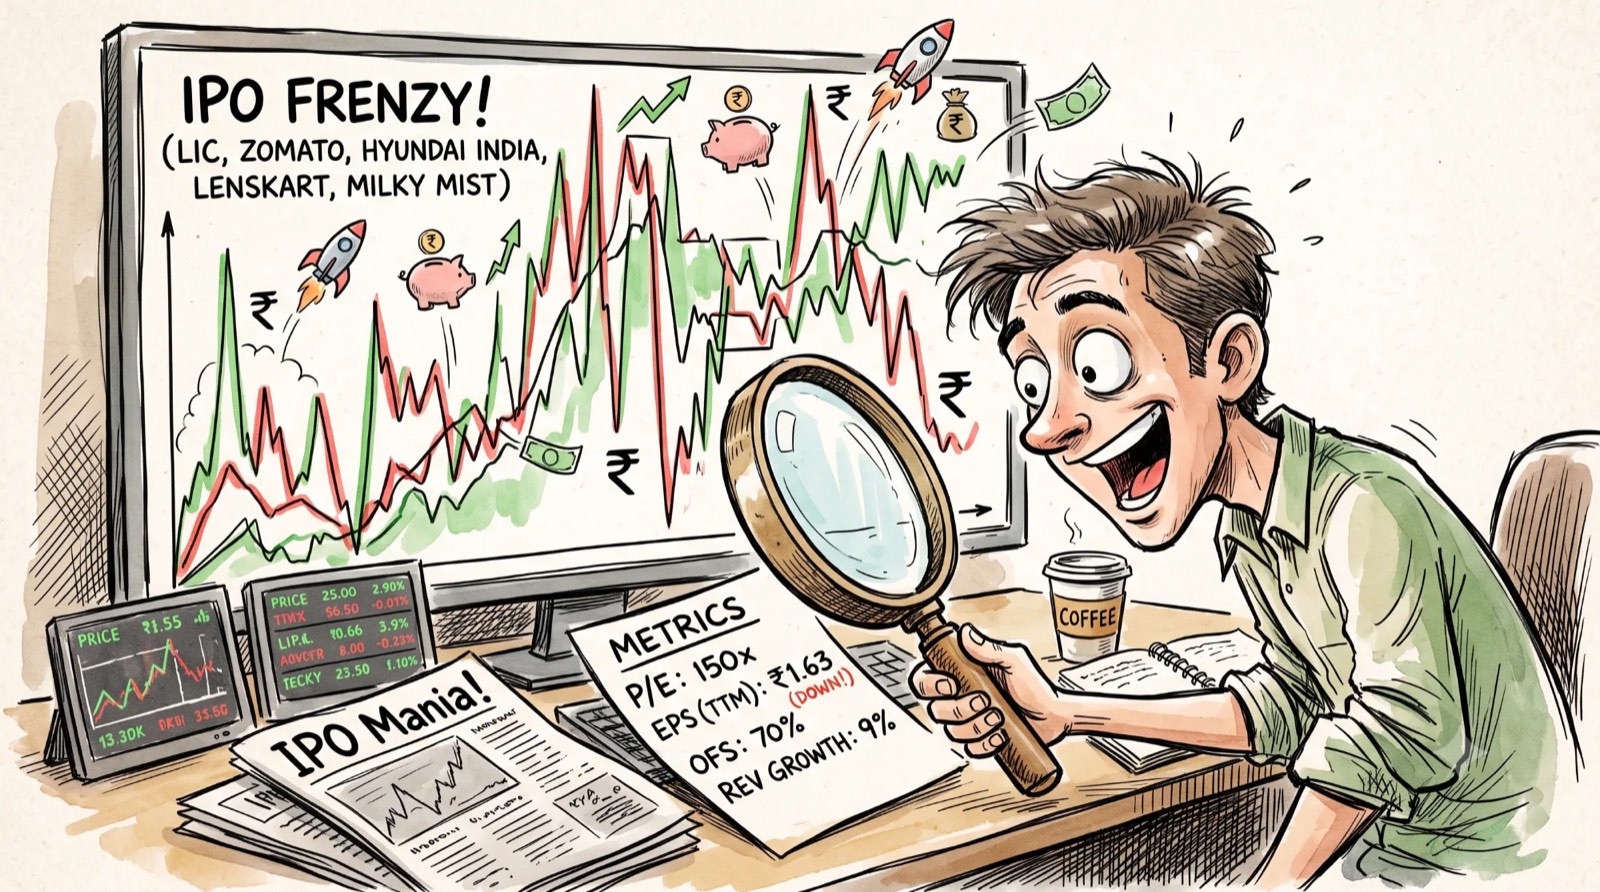
I wanted to start this series with the IPO frenzy we have been seeing in India over the last few years.
In short: India has seen 90 to 100+ mainboard IPOs a year since 2024. Many recent listings were priced at P/E ratios of 80 to 230, which means you pay today for years of growth that has not happened yet. Before applying, check the P/E, how much of the issue is an Offer for Sale, and whether the business can hold its margins against competition.
The Post-COVID IPO Boom in India
If you look at the data from the last decade, the number of Initial Public Offerings hitting the market has shot up alongside the huge increase in new retail investors.
As of September 2026, this year alone has seen 96 IPOs, putting us on track to get close to the highs of 2024 (which had 91) and 2025 (which saw 103). For context, the 12-year average is about 49 a year.
Lately, we have seen a risky trend where investors apply blindly for almost every IPO, hoping it will be the next big wealth generator. High-profile names like LIC, Zomato, Nykaa, Jio, Paytm, NSE, Hyundai and Lenskart have kept the excitement alive.
But what are you actually buying into when you bid? Let's ignore the marketing and focus on three basic metrics: the Price-to-Earnings (P/E) ratio, revenues and margins. The P/E ratio is simply the share price divided by the earnings per share (EPS), so it tells you how many rupees you are paying for every rupee of profit.
Let's look at three examples I've tracked to see what today's market valuations are actually forcing you to assume.
1. Lenskart IPO: Banking Heavily on the Future
- Issue Price: ₹402 | Listing Price: ₹395 | Current Market Price: ₹655
- Valuation at Listing (Nov 2025): P/E of ~230 ➔ Current P/E: ~150
A P/E of 230 means you are paying ₹230 upfront for every single rupee the company earns after expenses and taxes. Investment bankers price it this way because the company maintained a roughly 50% compound annual growth rate (CAGR) over the previous five years. Post listing, its Earnings Per Share (EPS) grew from ₹1.77 to ₹4.4 over the trailing twelve months, which brings the current P/E close to 150.
Even if Lenskart continues expanding at this incredibly fast pace, it will take another 5-6 years just to bring that valuation down to a reasonable level. That means you are paying premium prices today for growth that hasn't happened yet, leaving no room for errors or intense competition from Titan, Specsmakers and local opticians.
Furthermore, 70% of the ₹7,278 Cr IPO was an Offer for Sale (OFS). In an OFS, existing shareholders sell their shares, so the money goes to them and not to the company. Here, ₹5,128 Cr went straight to early investors exiting the company, not into expanding the business.
2. Milky Mist IPO: Great Products vs. Expensive Valuations
- Issue Price: ₹140 | Listing Price: ₹165 | Current Market Price: ₹328
- Valuation at Listing (Aug 2026): P/E of ~84 ➔ Current P/E: ~201
The stock price has nearly doubled since its recent listing, but the underlying numbers tell an interesting story. The listing P/E of 84x at a ₹165 price point was based on an EPS of roughly ₹1.96. Today, the trailing EPS has actually dropped to ₹1.63, meaning the company's earnings have cooled off even as the stock price climbed. This pushes the P/E to a whopping 201 times.
I use these products in my own home and have loved watching the brand grow from a basic paneer manufacturer into a full dairy lineup. But loving a product shouldn't be the only reason you buy a stock. Valuations are what ultimately dictate your long-term capital gains.
Do you think they can maintain high margins while scaling up, when they go head-on against deep-pocketed giants like Amul, Nandini, Hatsun and Heritage?
3. Hyundai Motor India IPO: The Mature Corporate Giant
- Issue Price: ₹1,960 | Listing Price: ₹1,931 | Current Market Price: ₹1,915
- Valuation at Listing (Oct 2024): P/E of 26.3x ➔ Current P/E: 31.5x
The math: Hyundai earns roughly ₹61 per share.
Unlike Lenskart or Milky Mist, 100% of this IPO was an Offer for Sale, meaning all the proceeds went back to the South Korean parent company instead of the Indian business.
Today, with the P/E at approximately 31.5x against a stock price of ~₹1,915, the trailing EPS works out to roughly ₹61. At listing, the same number was closer to ₹75. This tells us that Hyundai's earnings have actively declined since it went public.
The reality check: Hyundai has a strong balance sheet and does not lack cash. However, it is a mature player in a mature market, with volumes growing around 5% to 5.5% a year over the past decade, while revenue grew by 8-9% over the same period.
With Maruti holding about 41% of the market, followed by Mahindra at 15%, Tata Motors at 14% and Hyundai at roughly 15%, this is not a fast-moving startup that can easily outgrow a drop in earnings. At a 31.5x P/E, you need to consider whether their EV plans or cost-cutting measures can genuinely justify paying a premium multiple for a company with shrinking short-term profits.
The Big Picture: How to Think About Any IPO
Valuation is a subjective game. The growth story one person believes in might not look the same to you or to me. Before jumping into the next marketed IPO hype, it is worth taking a step back.
We have access to excellent digital tools today that can pull up key metrics and statistics in less than a minute. Use them to understand exactly why a company is choosing to go public, and try to map out where the business will realistically stand a decade from now. A few questions worth asking:
- What is the P/E at the issue price, and how many years of growth does it take to justify it?
- How much of the IPO is an Offer for Sale? Is the money building the business or paying out early investors?
- Are earnings actually growing since listing, or is only the share price going up?
- Can the company protect its margins against bigger, better-funded competitors?
Investing is a marathon, not a sprint. True wealth creation usually takes at least 8 to 10 years. Chasing short-term listing gains or small market movements rarely works out better than holding good companies that compound their assets over time.
As the legendary Charlie Munger once said:
"Why should it be easy to do something that, if done well two or three times, will make your family rich for life?"
As your financial guide, my job is to make sure your capital is not exposed to temporary market frenzies. If you want a share in tomorrow's big businesses without betting on a single IPO's valuation, a steady SIP in a well-diversified mutual fund lets professional fund managers do that vetting for you. Think through the numbers before you part with your money.
Disclaimer: This write-up reflects my personal views as of the date of writing, based on my current information and understanding. The companies mentioned are used only as examples. Nothing here is a recommendation to buy, sell or apply for any stock or IPO, and it is not formal financial advice. Mutual fund investments are subject to market risks; read all scheme-related documents carefully.